



Hello Phenom Fam,
Every week, a share of the rake from our tables goes to the people who stake $PHNM. Today we're giving $PHNM more utility, with a new way to turn it into liquidity: the PHNM Credit Pool.
Hold staked $PHNM? Unlock liquidity by borrowing USDC against your stake, while its rewards keep coming in and pay the interest. Hold USDC? Earn an attractive yield in a first-of-its-kind lending pool, with minimal exposure to the price of $PHNM and no price liquidations.
The difference is what the loans are built on. Every loan is backed by what $PHNM earns, not by what it's trading at, so swings in its price can't liquidate anyone. And the interest lenders earn is paid out of poker revenue, not out of someone else's leverage.
The pool opens to lenders first. Join the lender list and we'll email you the day deposits open.
At a glance:
- Lend USDC and earn interest paid from poker revenue.
- Borrow USDC against staked $PHNM, and let its rewards pay the interest.
- No price liquidations. A falling $PHNM price never triggers anything.
- Your choice of terms. Lend Flexible, or lock a six-month Term that can renew itself. Loans have no end date.
- On Base, open to any wallet. No KYC.
Real yield lending: why this is a game changer
Most lending in DeFi is built on price. You post collateral, borrow against what it's worth today, and if it's worth less tomorrow, a bot sells it. That keeps lenders whole most of the time, but it makes the system fragile. One sharp drop sets off a wave of liquidations, and every forced sale drags the price lower for everyone else. And because most stablecoin yield comes from people borrowing to place bets, it dries up the moment the market turns.
Staked $PHNM gives us something steadier to lend against: a share of Phenom Poker's revenue, paid every week whatever the token is doing. So the pool sizes each loan by what its collateral earns, and those earnings pay the interest. That's real yield: income from a working business, passed from borrowers to lenders.
Price plays a single role, as a ceiling. A new loan can't be worth more than 75% of its collateral, measured at the four-week average price. After that, price never decides anything.
Earn real yield on USDC
Where your yield comes from
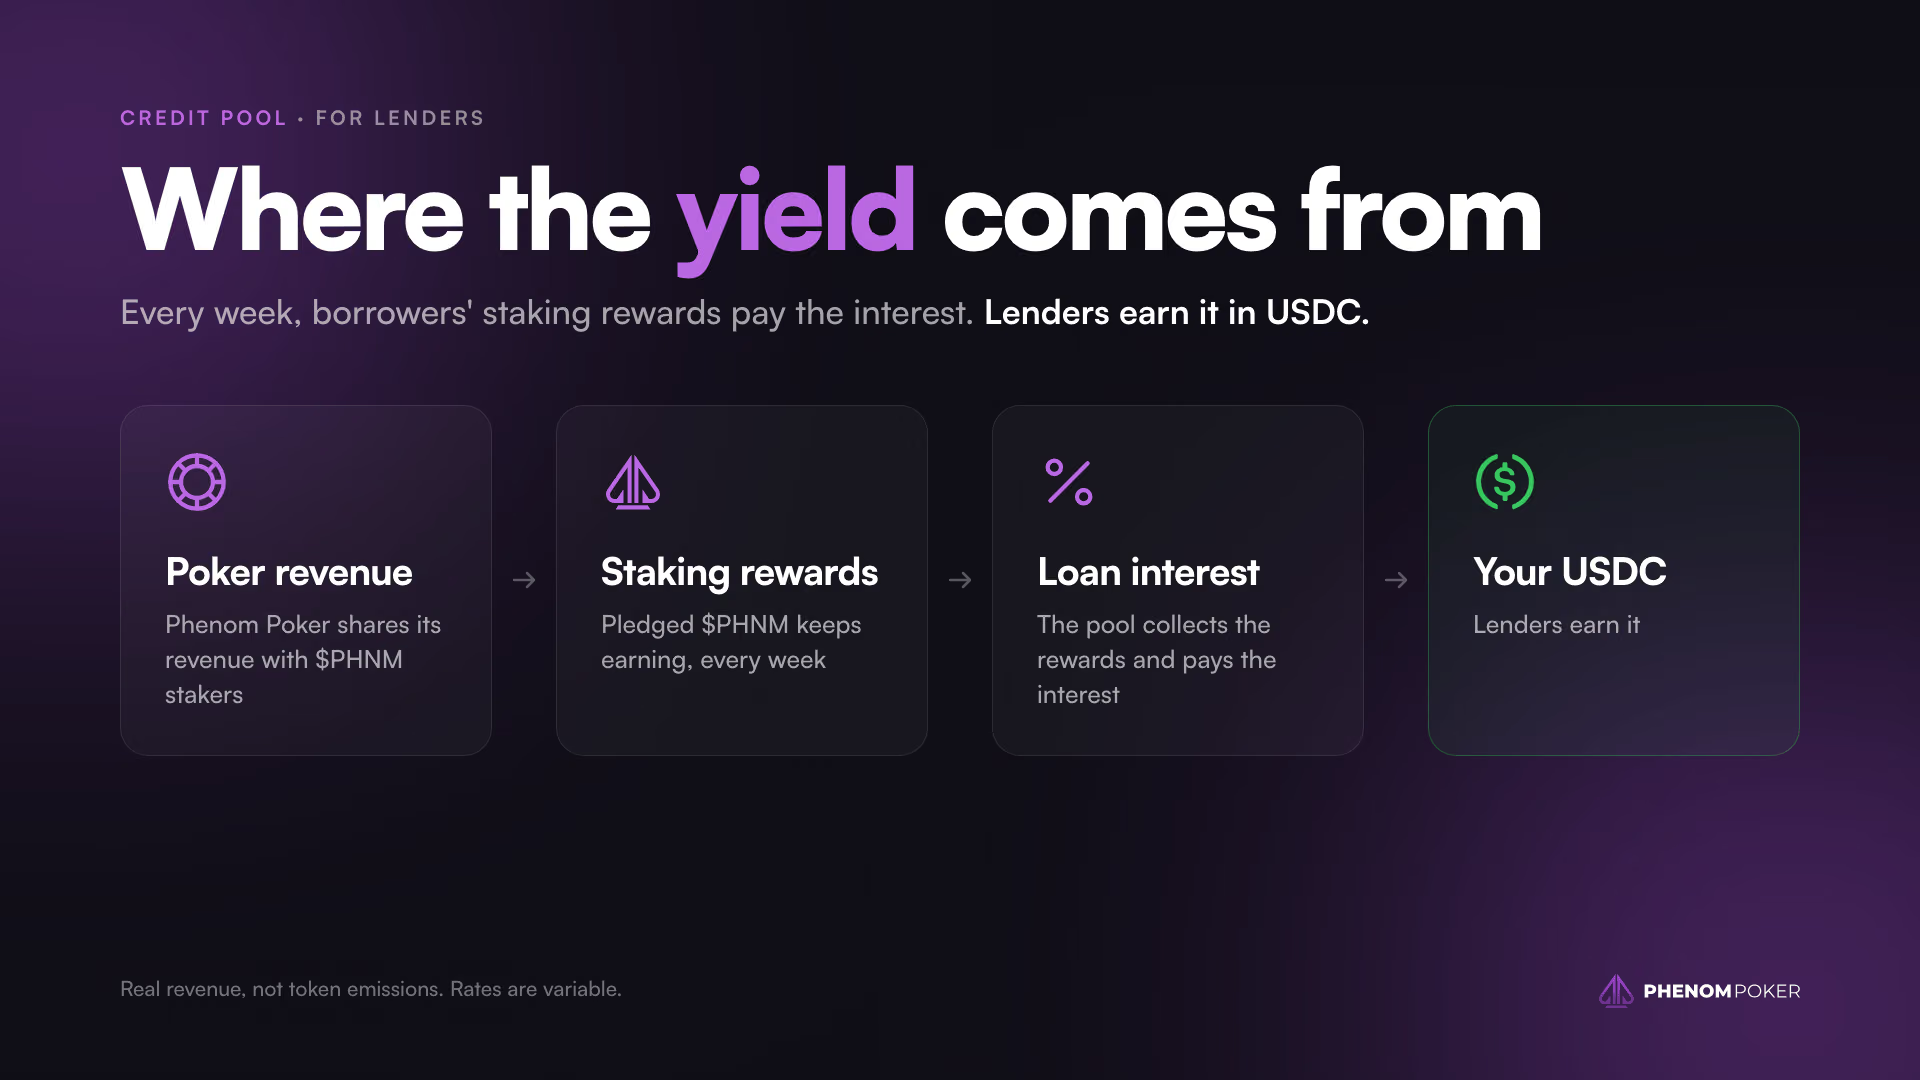
Players pay rake on every pot, and Phenom shares part of that revenue with $PHNM stakers every week. When a staker borrows from the pool, their $PHNM keeps collecting those rewards. The pool claims them, converts them to USDC and uses them to pay the loan's interest. That interest is what you earn.
None of it depends on new deposits coming in, or on a token we mint to pay you. As long as people are playing poker, the interest has a source.
Your interest is added to your deposit as it's earned, so it compounds on its own. There's nothing to claim.
How your deposit is protected
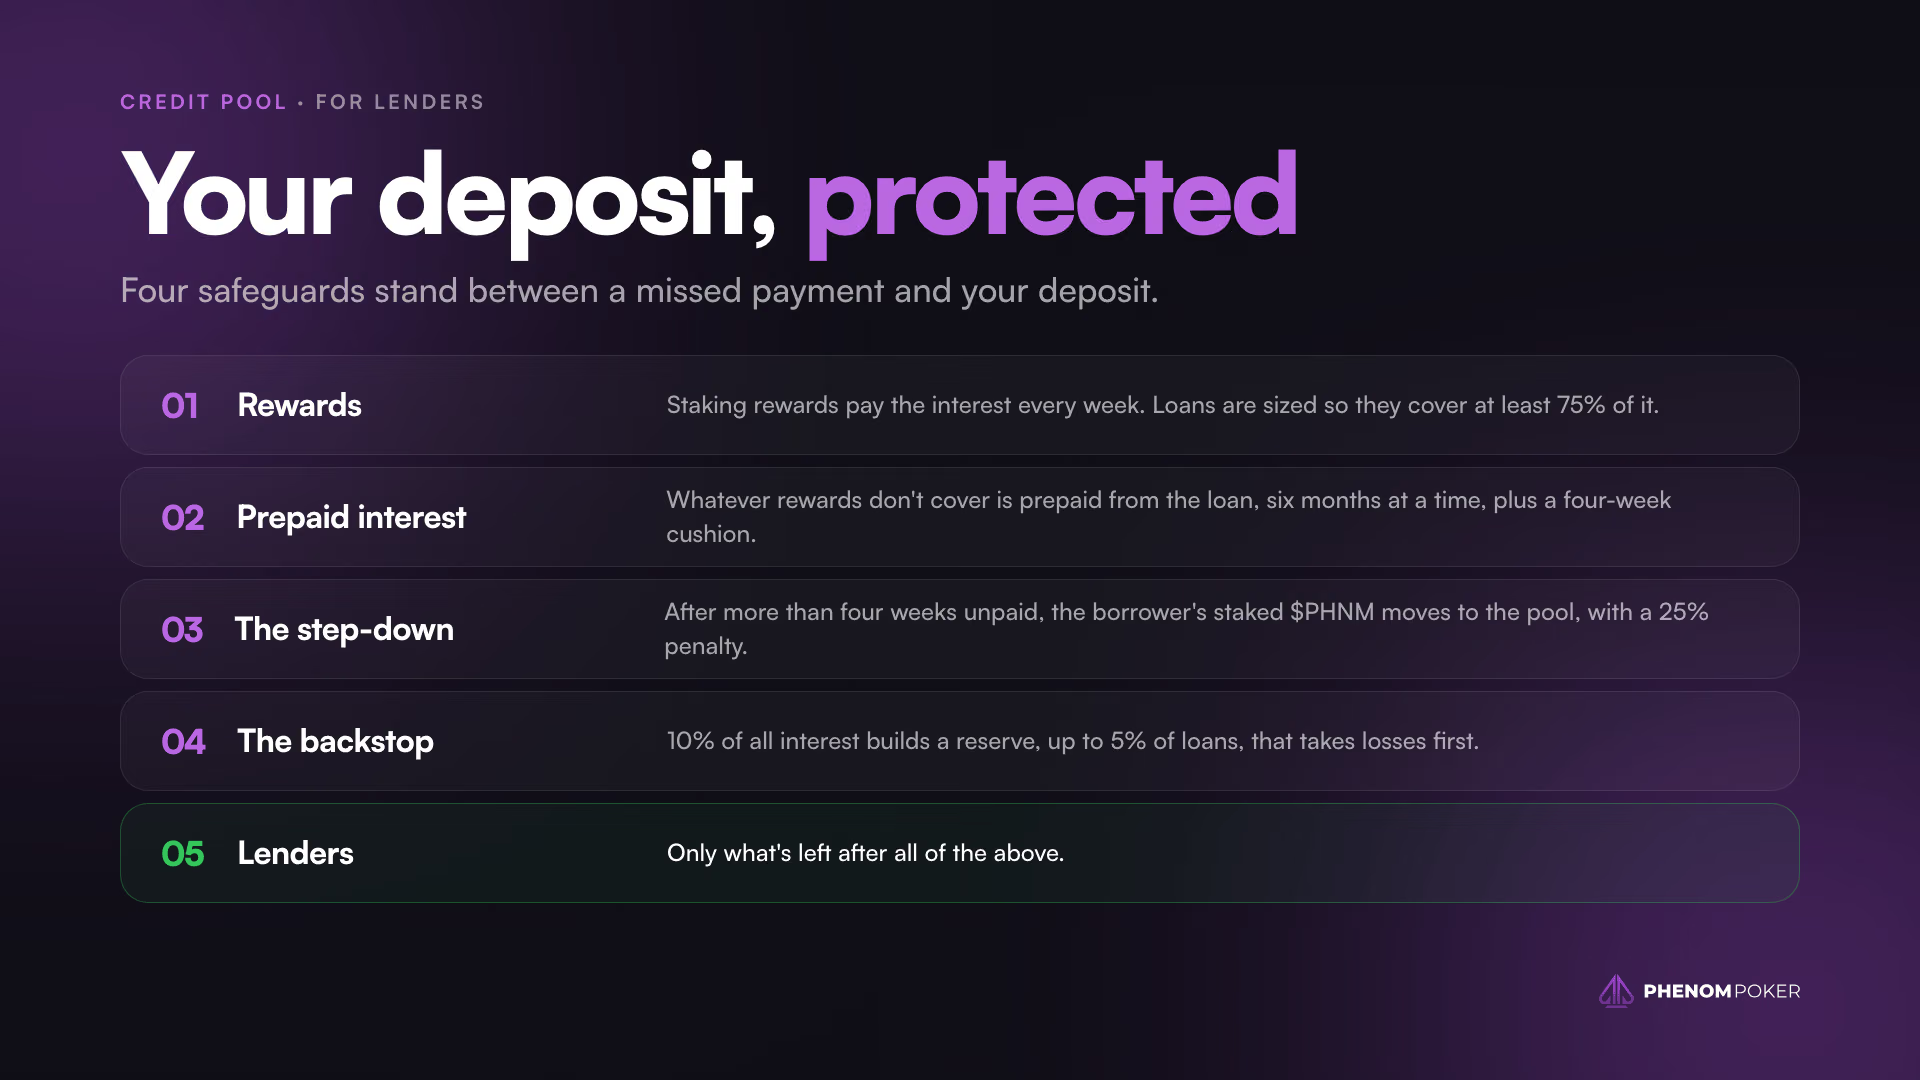
Four safeguards stand between a missed payment and your deposit:
- Rewards. A loan can only be opened if its rewards cover at least 75% of the interest at the pool's top rate. Most loans will be covered more than once over.
- Prepaid interest. Whatever the rewards don't cover, the borrower pays up front out of the loan, six months at a time, with a four-week cushion on top.
- The step-down. If a borrower still lets more than four weeks of interest go unpaid, enough of their staked $PHNM moves to the pool to shrink the loan to a size its rewards can carry. They also pay a 25% penalty on the amount cleared, most of which goes to lenders.
- The backstop. 10% of all interest builds a backstop, up to 5% of all loans, which absorbs losses before lenders do.
We modelled the pool over two years and 2,000 revenue paths. Lenders only lost money when poker revenue and the price of $PHNM both fell hard and borrowers walked away from their loans.
No price liquidations
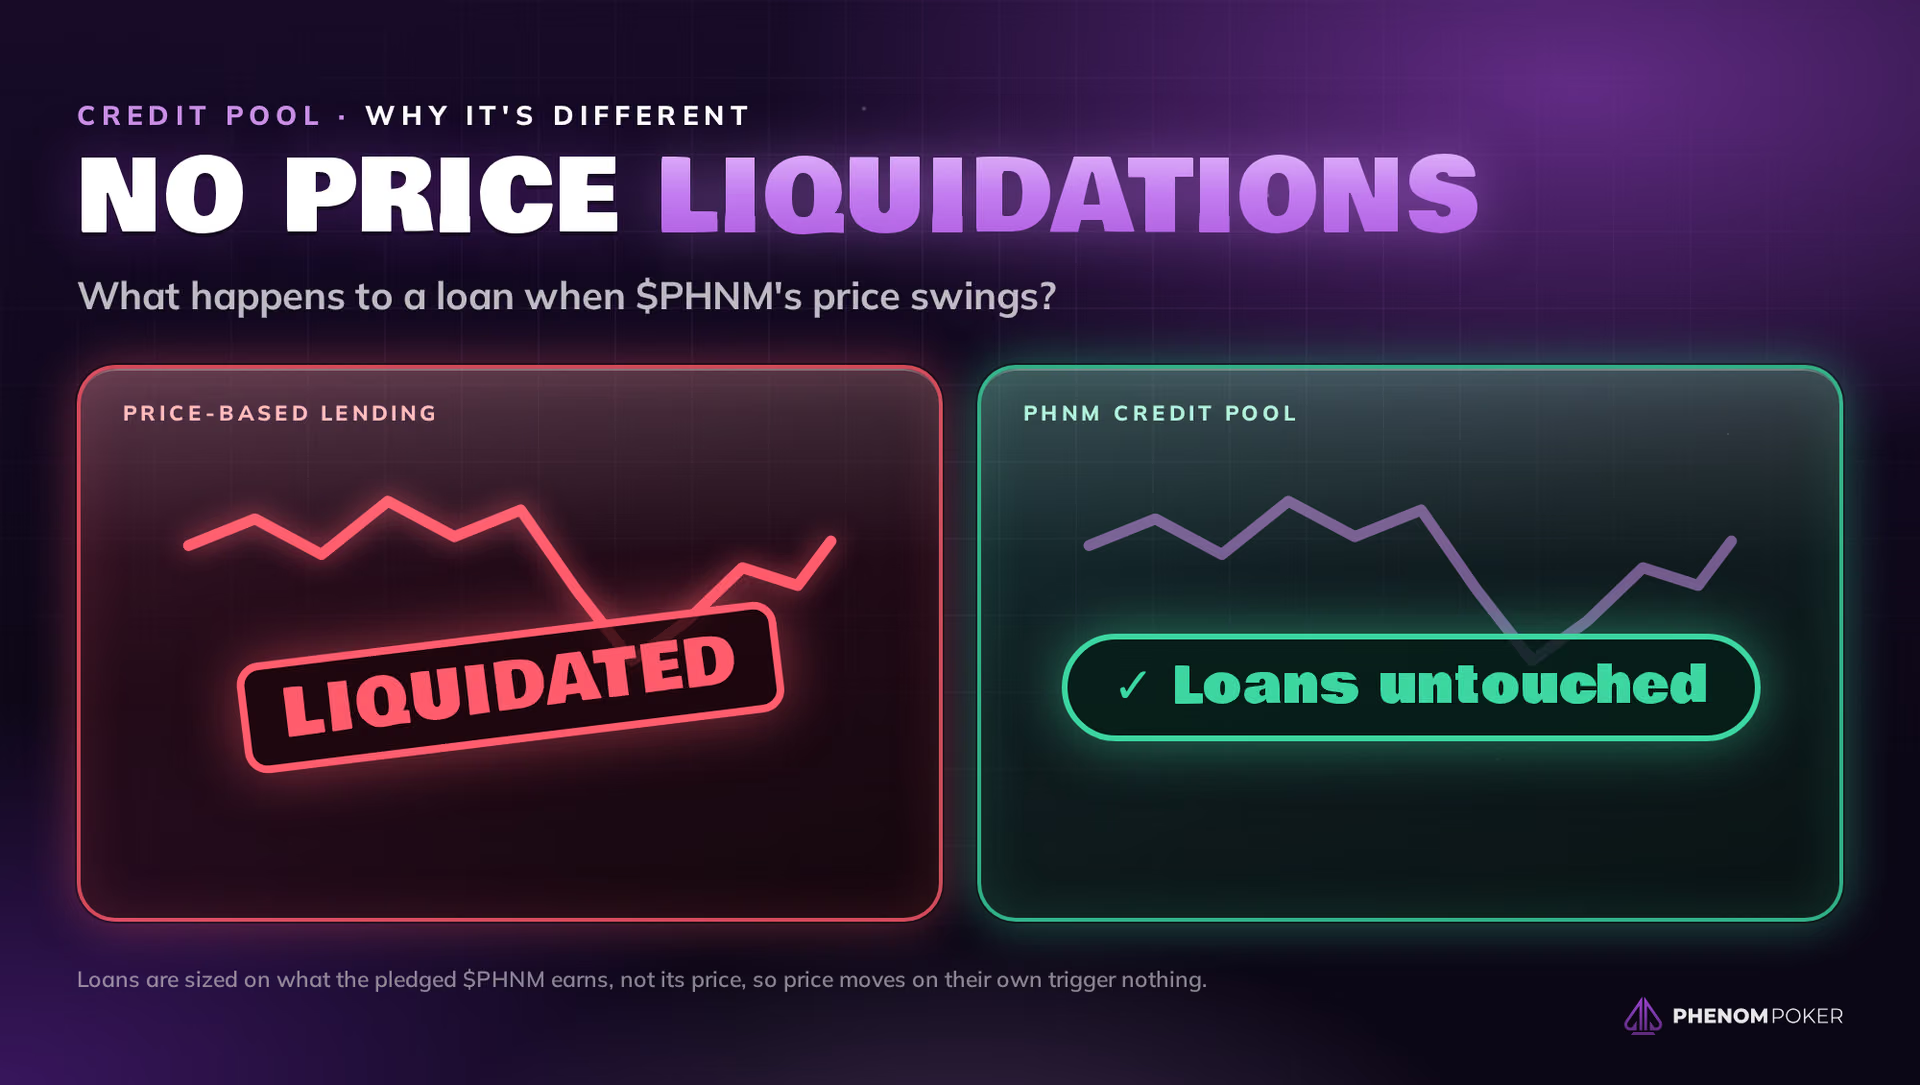
Price-based pools protect lenders by selling collateral fast. That works until the market moves faster: in a sharp drop, liquidations pile up, the collateral sells for less and less, and any shortfall lands on lenders. The Credit Pool takes that failure mode off the table. There are no liquidation bots waiting for a dip, no cascades, and nothing to gain by pushing the price around.
If a loan does step down, the $PHNM the pool takes is never sold on an exchange. It stays staked, is locked for two years and is held in the Pool Reserve on lenders' behalf. Buyers can purchase it as locked positions, and each sale turns it back into USDC for lenders.
How the rate is set
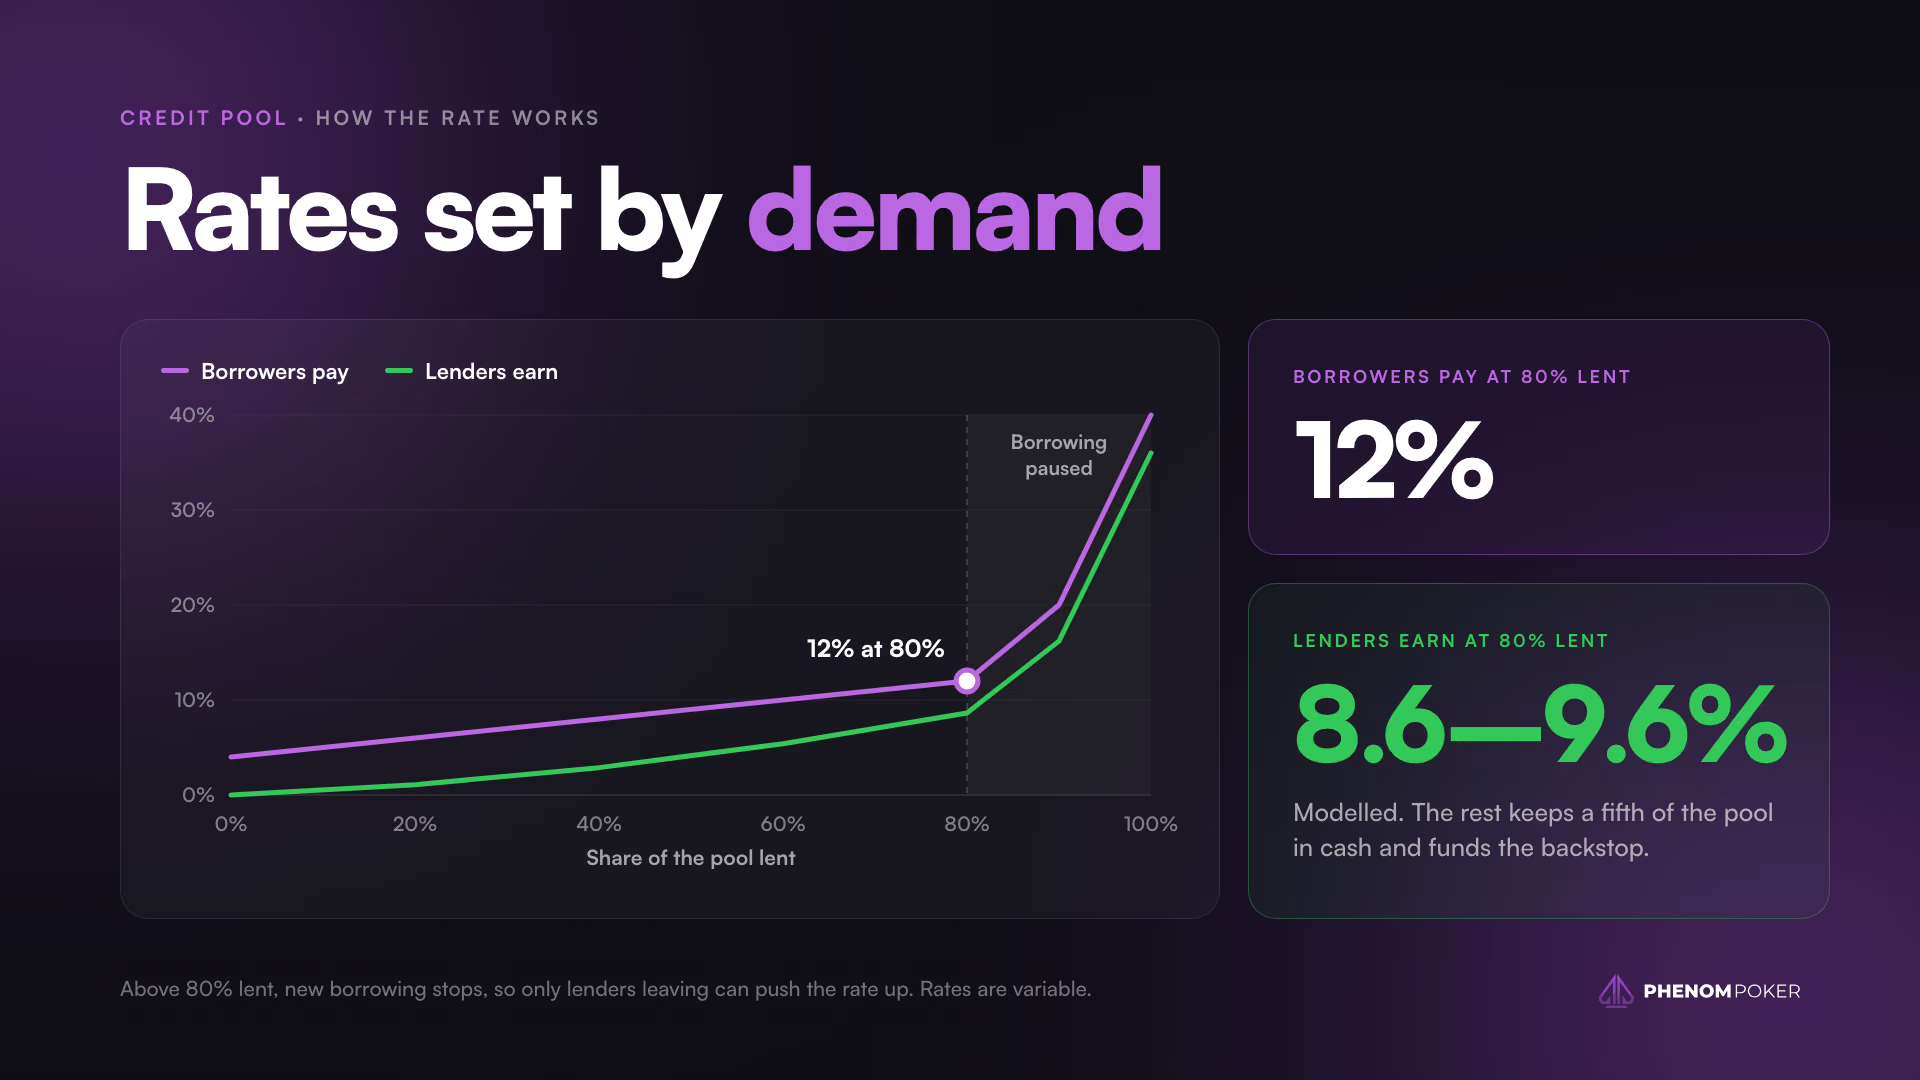
The rate follows how much of the pool is lent out: 4% when it's empty, 12% when it's 80% lent. At 80%, new borrowing stops, which keeps at least a fifth of the pool in cash for withdrawals. Beyond that point, only lenders leaving can push the rate higher, and the higher rate is what brings new lenders in.
Lenders earn a little less than borrowers pay, because some of the pool sits in cash and 10% of interest goes to the backstop until it's full. Phenom takes nothing. In our model, lenders earn roughly 8.6% to 9.6% when the pool is 80% lent.
Flexible or Term
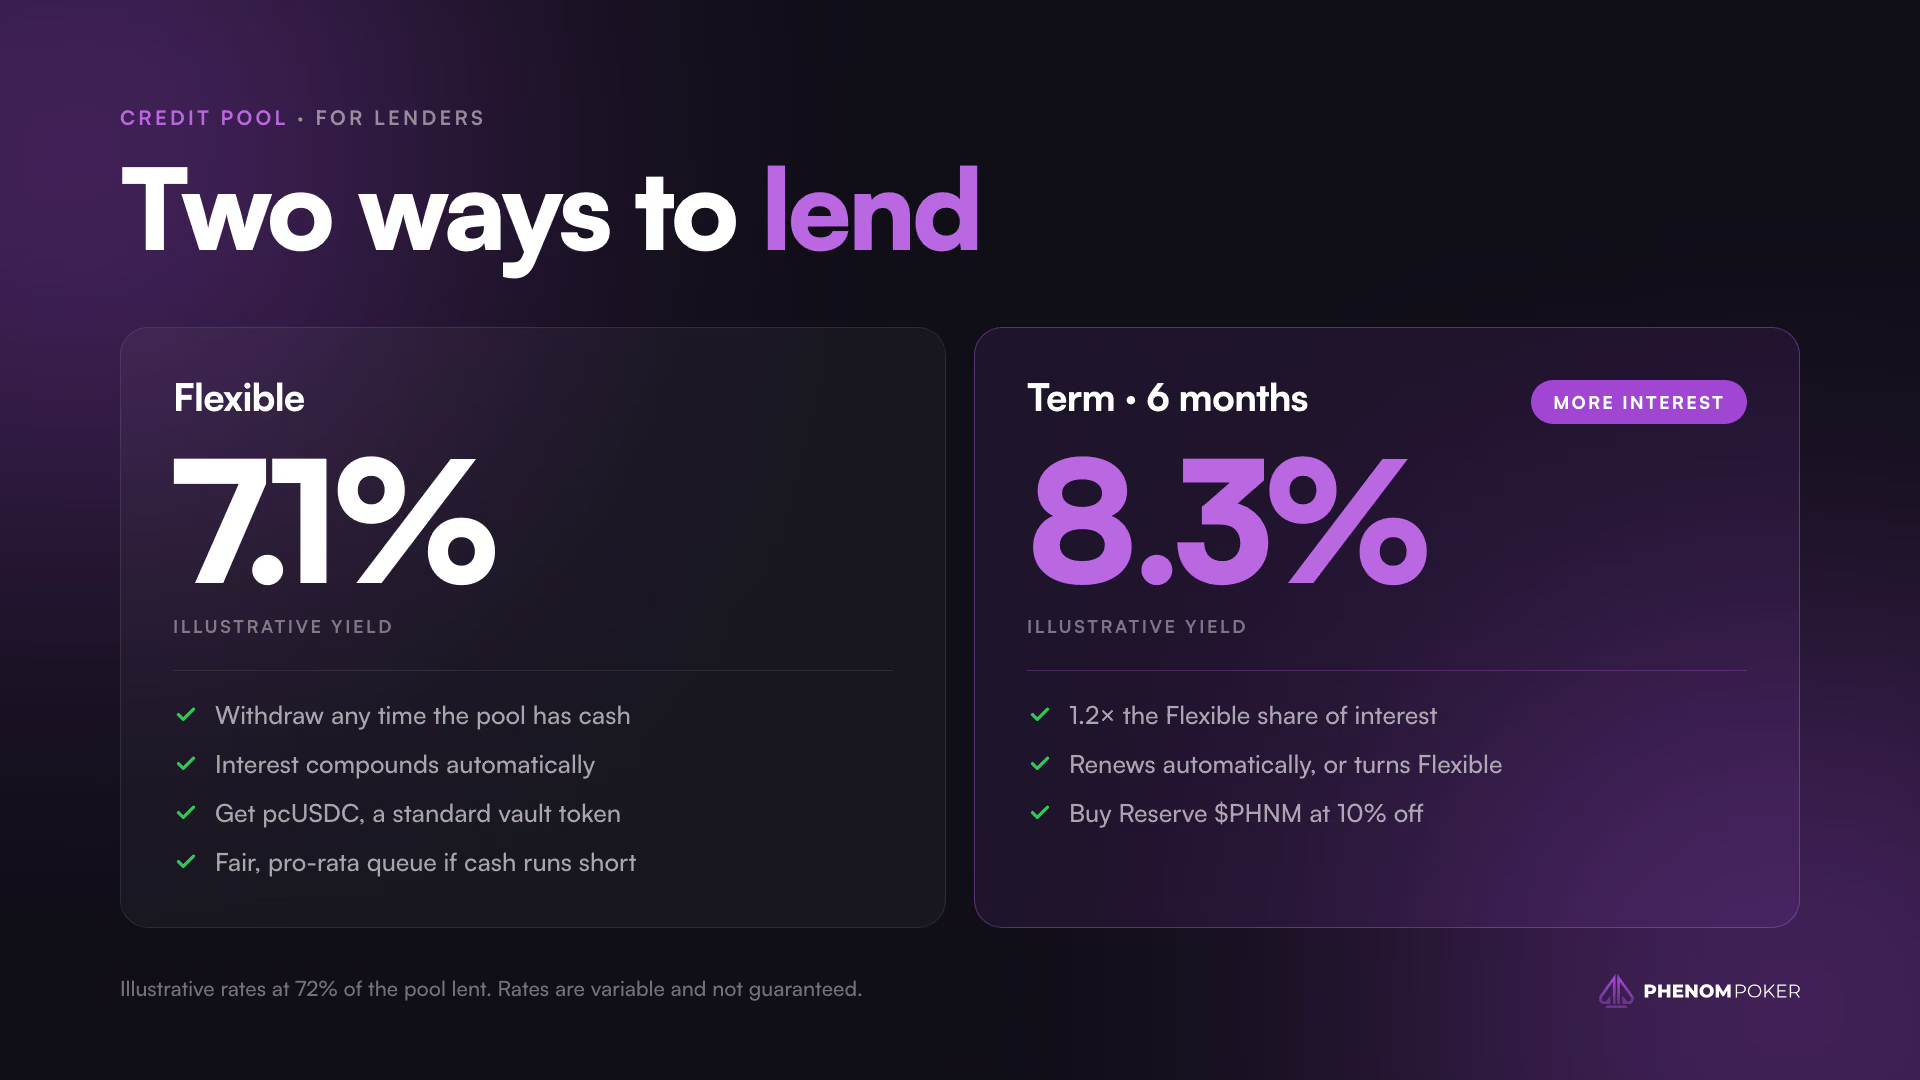
Flexible deposits can come out whenever the pool has cash. You receive pcUSDC, a standard ERC-4626 vault token you can hold or move like any other.
Term deposits are locked for six months and earn 1.2× the Flexible share of interest. Term lenders can also buy Reserve $PHNM at 10% off.
When the six months are up, you choose what happens. Set your Term to renew and it rolls into another six months on its own, with everything it earned, so you keep the higher rate. Otherwise it moves to Flexible, and you can withdraw whenever you like. You can change your mind any time before the term ends.
In our illustrative pool, with 72% lent, that works out to 7.1% for Flexible and 8.3% for Term. Rates move with demand and aren't guaranteed.
Terms at launch
Term | Launch setting |
Chain and asset | Base, USDC |
Collateral | Staked $PHNM, relocked for two years |
Loan size | Rewards must cover at least 75% of the interest at the top rate, and the loan can't exceed 75% of collateral value (four-week average price) |
What triggers a step-down | More than four weeks of unpaid interest, after prepaid interest and the cushion. Never price |
Penalty | 25% of the amount cleared (20% to lenders, 5% to the backstop) |
Backstop | 10% of interest, until it holds 5% of loans |
Rate | 4% empty, 12% at 80% lent, up to 40% at 100%. New borrowing stops at 80% |
Term deposits | Six months at 1.2× the Flexible share of interest. Renew automatically, or move to Flexible at maturity |
Borrowing fee | 1% (0.5% to refinance) |
Per-borrower cap | 10% of the pool |
Price feed | Time-weighted prices from the $PHNM/USDC pool on Aerodrome. Used to size new loans and value pool $PHNM, never to liquidate |
Changes | Through a public timelock, with hard limits in the code |
Access | Any wallet. No KYC, sanctions screening only |
Built to protect lenders
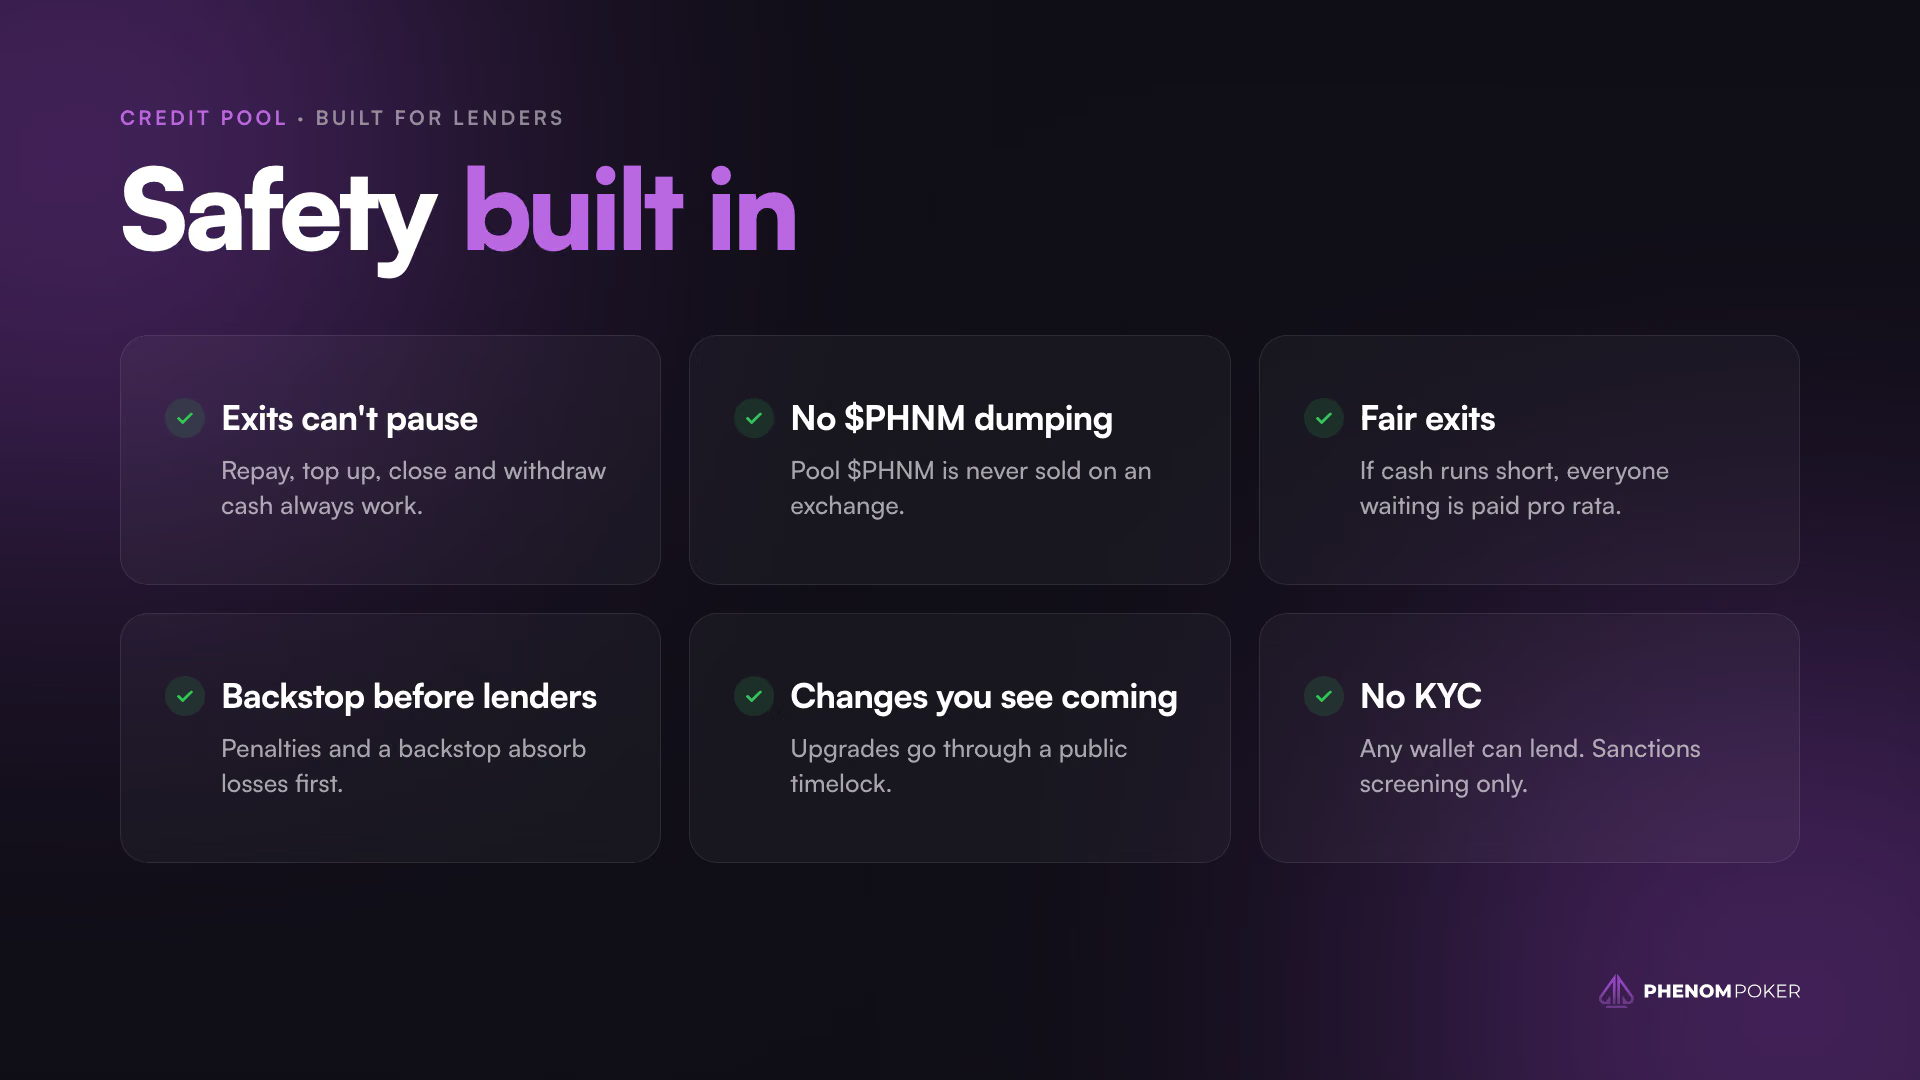
- Exits can't be paused. Repaying, topping up, closing a loan and withdrawing cash always work. A pause can only stop new deposits and new loans.
- Exits are fair. If withdrawals ever outrun the cash, everyone in the queue is paid in proportion from every dollar that comes in. Rushing to the front gets you nothing, and money waiting in the queue keeps earning.
- No quick in-and-out. Income on a new deposit builds up over its first week, so nobody can drop in for a day to grab a week's interest.
- No surprises. Upgrades and changes to settings go through a public timelock.
We'll publish the contract addresses and the audit report before deposits open.
Unlock liquidity without selling
Keep your $PHNM, get USDC
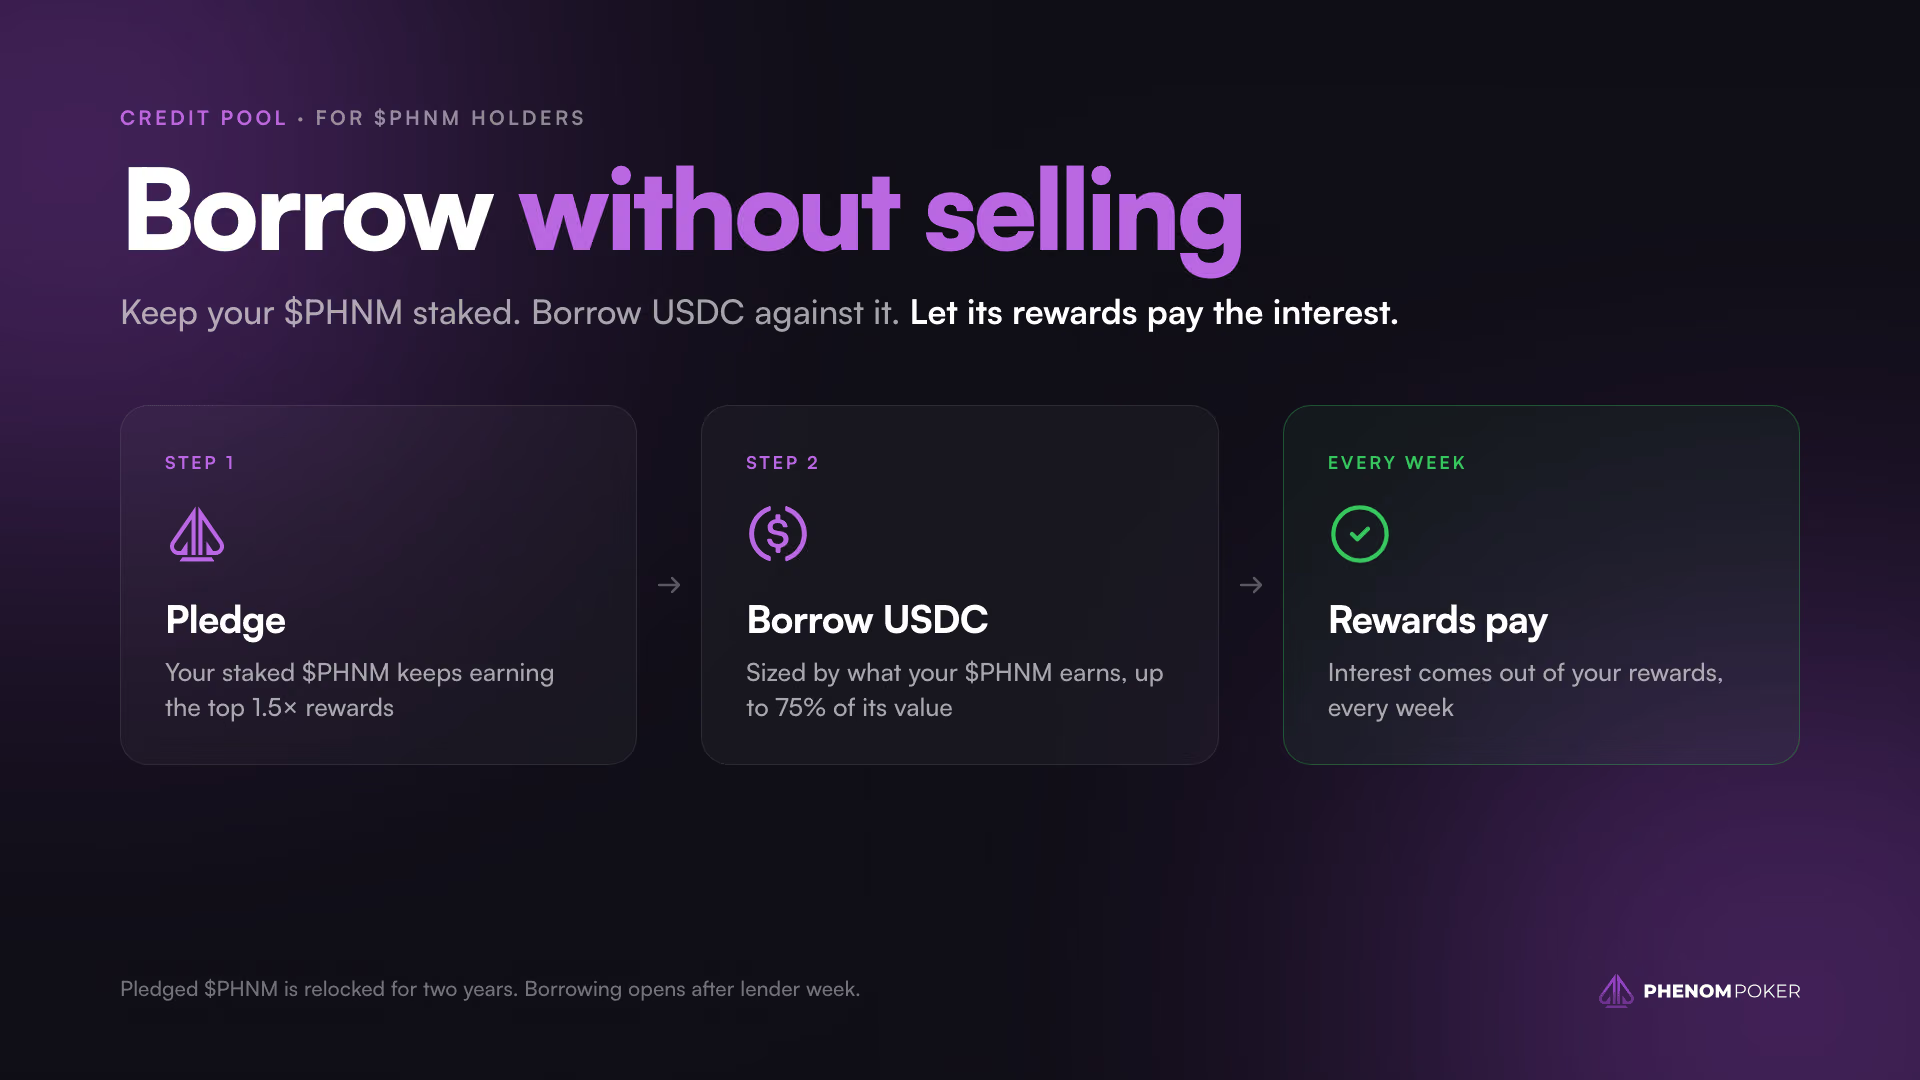
Until now, holding staked $PHNM and needing cash meant one of two things: sell, or wait for your lock to end. The Credit Pool adds a third option. Pledge your $PHNM, borrow USDC against it, and keep everything that makes holding it worthwhile. It stays staked at the top 1.5× rewards, and those rewards pay your interest every week without you lifting a finger.
At launch rates, you can borrow about nine times your stake's yearly rewards, up to 75% of its value.
A loan that looks after itself
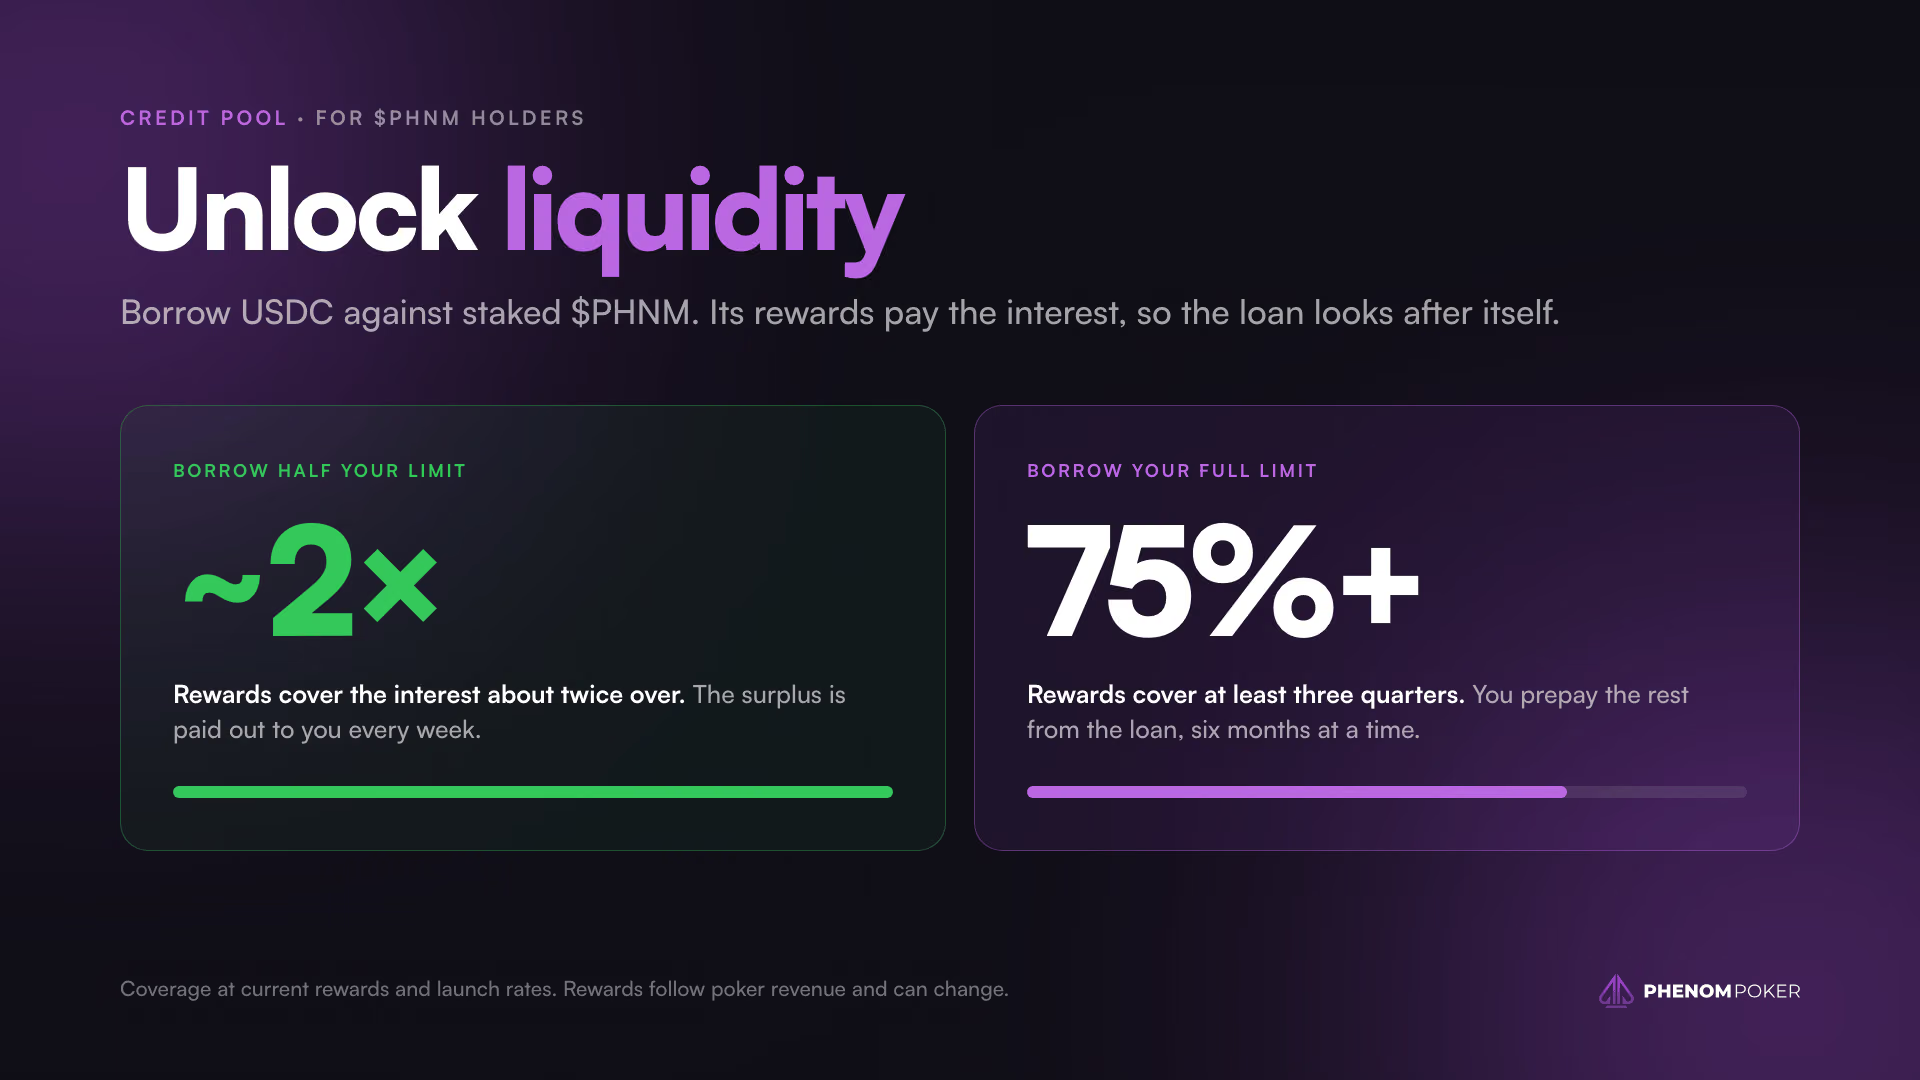
Borrow around half of what you're allowed and, at today's rewards, they'll cover your interest about twice over, with the extra paid out to you. Borrow the maximum and they still cover at least three quarters. The rest is set aside from the loan up front, six months at a time.
The thing that ends most crypto loans can't end yours, because the pool ignores price. If rewards slip, your prepaid interest and four-week cushion keep the loan current, and the app shows you exactly where you stand. Only after more than four weeks of unpaid interest does anything happen, and even then the loan gets smaller instead of closing.
On your terms
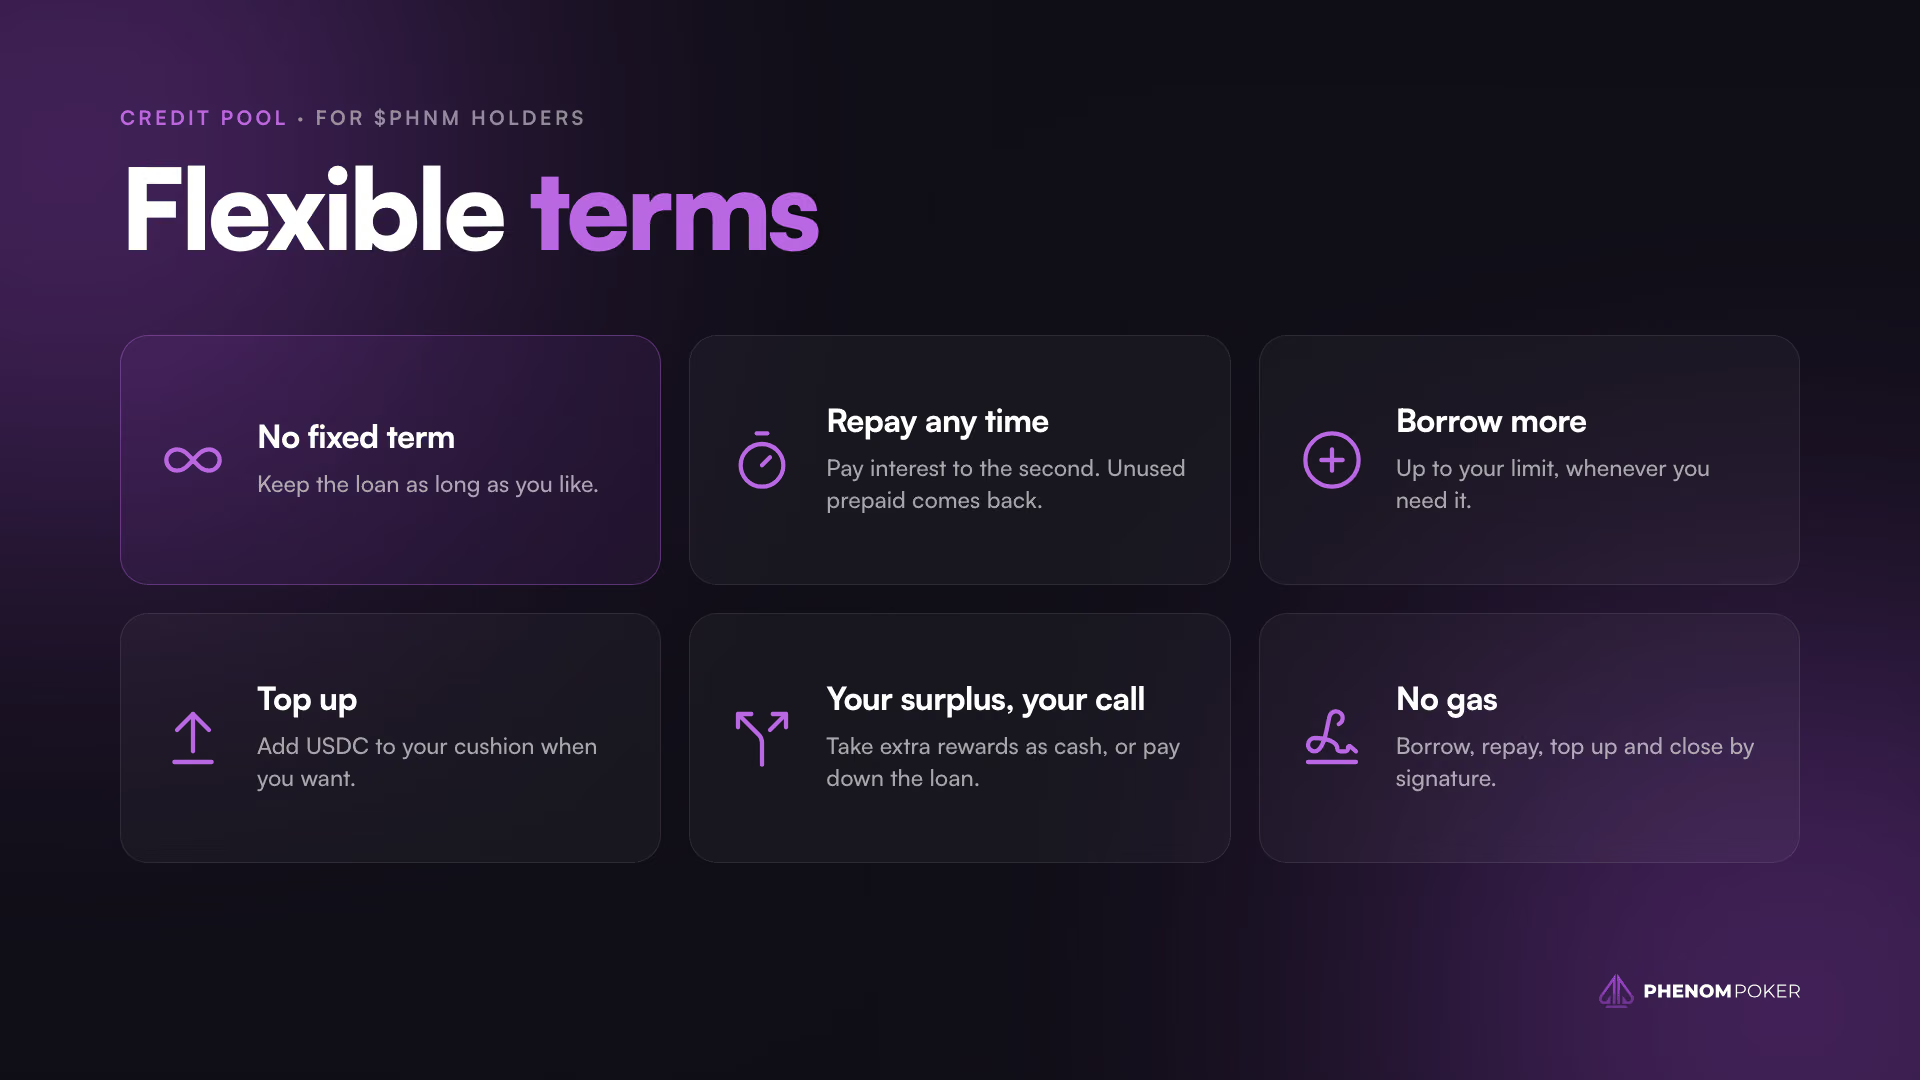
There's no end date. Repay whenever you like and you pay interest only up to that second; any prepaid interest you didn't use comes back to you. You can borrow more up to your limit, top up your cushion, and choose whether extra rewards are paid out to you or go toward the loan. Borrowing, repaying, topping up and closing all happen by signature, so you don't need ETH for gas.
Worth knowing before you pledge:
- Pledged $PHNM is relocked for two years and stays in the pool until the loan is repaid. When it comes out, it's relocked for two years again.
- Your rate moves with the pool. It's the market rate times a personal multiplier set when you borrow, from 0.9× for small loans to 1.2× at your limit.
- At launch, pledged $PHNM doesn't count toward your poker rakeback tier. The app warns you if a pledge would lower it.
- Borrowing opens the Monday after lender week, first come, first served.
The risks
We'd rather you hear these from us.
- Lenders can lose money. It takes a crash in the price of $PHNM and borrowers who stop paying, and the penalty and backstop absorb losses first.
- Loans are backed by rewards, not marked to price. After a big price drop, some loans can be worth more than the $PHNM behind them. We'll publish that figure.
- Lenders can end up holding $PHNM. If the Reserve grows past 15% of the pool, withdrawals include a share of it as staked $PHNM, so nobody is left holding it alone.
- Rewards depend on poker revenue. If revenue falls, rewards fall, borrowers top up more and more loans step down.
- Withdrawals can wait. If the pool runs short of cash, Flexible withdrawals go through the queue.
- Rates move. The yields shown here are illustrations, not promises.
- Smart contract risk. Any contract can have bugs.
Be first in
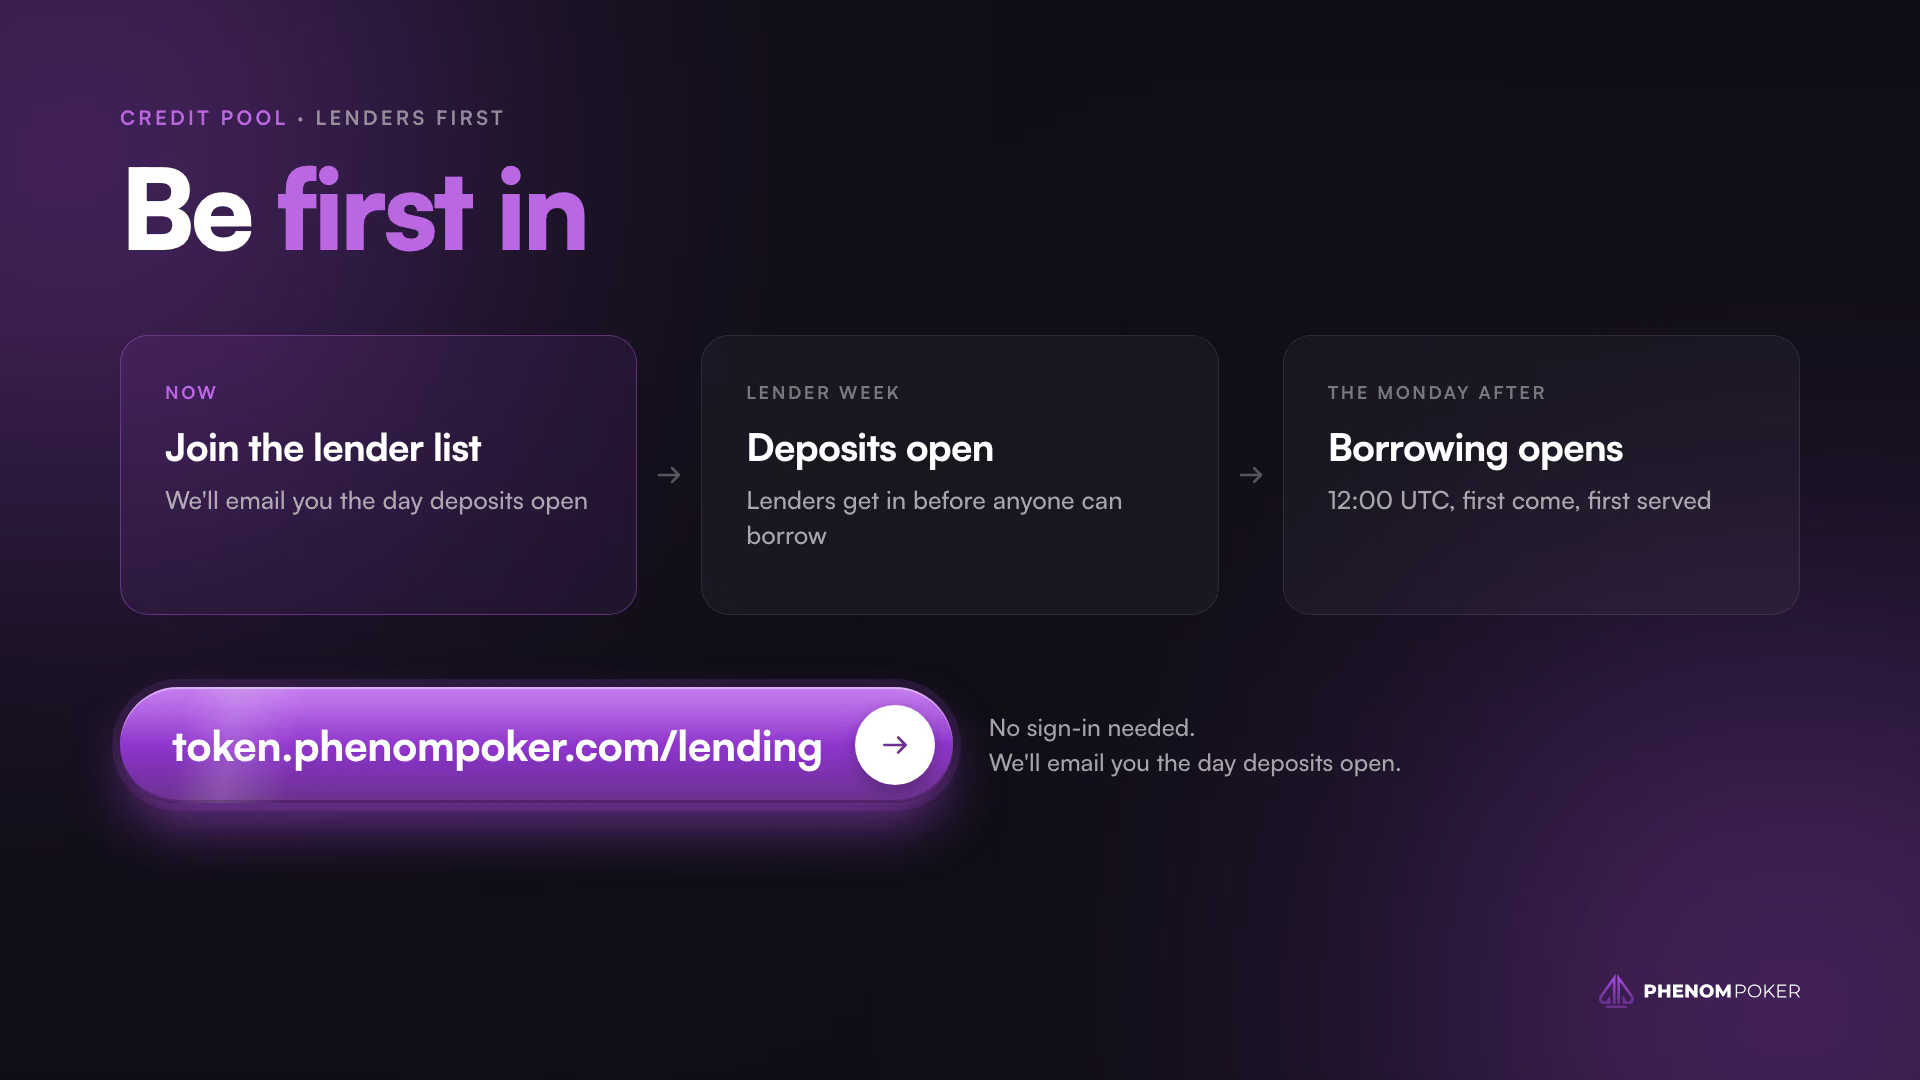
Lenders get a full week before anyone can borrow, so the pool is funded on day one.
Join the lender list at token.phenompoker.com/lending. Leave your email, no sign-in needed, and we'll tell you the day deposits open. If you let us know roughly how much you'd like to lend, it helps us size the pool for launch.
Questions? Come find us on Discord or Telegram.
FAQ
What backs the loans?
The weekly staking rewards on the borrower's $PHNM, which pay the interest, and the staked $PHNM itself as collateral.
Can a falling $PHNM price liquidate a loan?
No. Only unpaid interest can shrink a loan, and only once more than four weeks of it has built up.
Where does the yield come from?
From borrowers' interest, which is mostly paid by the staking rewards on their pledged $PHNM. Those rewards come from Phenom Poker's revenue.
What if a lot of lenders want out at once?
Withdrawals are instant while the pool has cash, and new borrowing stops at 80% lent to keep cash on hand. As the pool fills up, the rate rises and draws cash back in. If cash still runs short, the queue pays everyone in proportion.
Do I need KYC or a Phenom Poker account?
No. A wallet with USDC or staked $PHNM is enough. The only check is a sanctions screen.
Does Phenom take a cut?
No. Interest goes to lenders and the backstop, and the 1% borrowing fee goes to the backstop too.
The PHNM Credit Pool isn't live yet. How it works, and the rates, may change before launch. Nothing here is an offer to lend or borrow, or financial advice. All figures are illustrative.